Life insurance is one of those financial topics that is incredibly important while also being, let's be honest, pretty boring. And life insurance ladders are no different.
Nobody really wants to think about it. And once you have your policy in place, ideally you don't need to think about it very much at all.
But there is one wrinkle to term life insurance that comes up fairly often, particularly for physicians. And that is, you guessed it, life insurance ladders.
When I was first learning about insurance, I basically thought about term life insurance as a single decision. Figure out how much coverage you need, decide how long you need it, buy a policy, and move on. And honestly, that is still a perfectly reasonable approach. It is essentially what I did.
However, life insurance ladders can be a useful strategy for some physicians because our need for life insurance usually isn't static. It changes throughout our lives and careers.
So let's talk about exactly what a life insurance ladder is, how it works, its limitations, and who should actually consider using one.
- Carlton Lane works exclusively in accredited, private-market real estate.
- The firm operates independently of sponsors, fund families, and proprietary products.
- Independent third-party diligence firms re-underwrite opportunities, stress assumptions, and surface risks.
- Carlton Lane focuses on set-term projects with a clear investment thesis and patient capital deployment.
First, a quick reminder about term life insurance
Before getting into life insurance ladders, we need to start with the underlying product.
Term life insurance is very simple. You buy a certain amount of insurance for a certain amount of time. If you die while the policy is active, the insurance company pays the death benefit to your beneficiaries. If the term ends and you are still alive, the coverage ends. That's it.
For example, you might purchase a $3 million 30-year term policy at age 32. If you die at 45, your beneficiaries receive $3 million. If you are alive when the policy expires at 62, the coverage simply ends.
And that simplicity is exactly why I like term insurance.
As I've written before in my guide to life insurance for physicians, if other people depend on your income, you need life insurance. And for the overwhelming majority of physicians, that means term life insurance.
I also include term life insurance among the insurance policies that doctors actually need.
This is very different from whole life or other permanent life insurance products that combine insurance with an investment or cash-value component. Those products are much more expensive and, in my opinion, unnecessary for the vast majority of physicians.
The National Association of Insurance Commissioners offers a useful consumer guide to life insurance explaining these distinctions as well.
With that foundation established, let's get to the ladder.
What is a life insurance ladder?
A life insurance ladder simply means owning multiple term life insurance policies with different expiration dates.
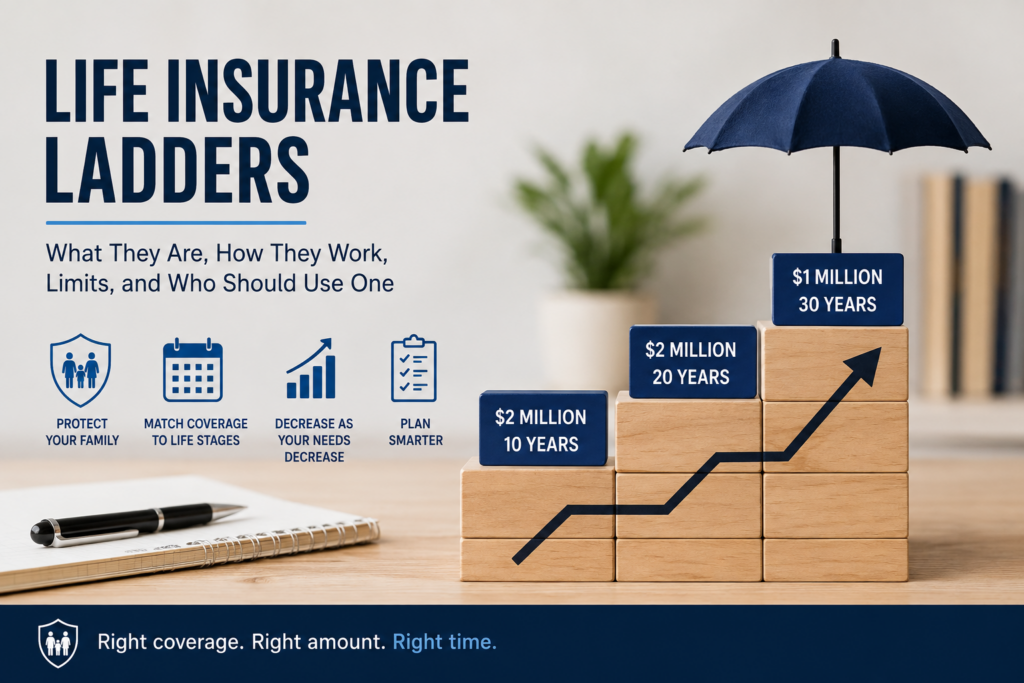
Instead of buying one $5 million policy lasting 30 years, for example, you might buy:
- $2 million for 10 years
- $1.5 million for 20 years
- $1.5 million for 30 years
For the first 10 years, you have $5 million of total coverage.
After the first policy expires, you have $3 million. After the second expires, you have $1.5 million. And after 30 years, you have no coverage.
Your life insurance therefore gradually decreases as your financial need for life insurance theoretically decreases.
That's the ladder.
And unlike some unnecessarily complicated insurance strategies marketed to physicians, there is nothing inherently gimmicky about this one. It is simply a way to match your insurance coverage more closely with your expected financial obligations over time.
Why would your life insurance needs decrease?
This is where the strategy starts to make sense.
Remember what life insurance is actually protecting against. Life insurance isn't really protecting against death itself. Obviously no amount of money fixes that. It's protecting your family against the financial consequences of losing you and, importantly, your future income.
Imagine a 35-year-old physician with a spouse and three young children.
The physician has a mortgage, plans to help pay for college, hasn't accumulated enough retirement savings yet, and provides a significant percentage of the household income.
If that physician dies tomorrow, the financial consequences could be enormous.
Now fast-forward 20 years.
The mortgage should be mostly or completely paid off. The kids may be through college. And the physician should have accumulated several million dollars in retirement and taxable investment accounts. Maybe there is real estate producing passive income.
The family still depends on the physician, but financially they are in a very different position.
That is the central idea behind laddering. Your need for life insurance is generally highest early in your career and decreases as you accumulate assets and eliminate liabilities.
A physician life insurance ladder in action
Let's use a hypothetical example.
Imagine a 33-year-old physician finishing training. She is married with two young children and expects to earn $500,000 annually as an attending.
After working through her family's financial needs, she determines that she wants $5 million of life insurance today.
But does she really need $5 million when she is 58? Maybe not.
She could therefore buy $5 million of 30-year coverage. There is nothing wrong with that.
Or she might construct a ladder:
- $2 million for 10 years
- $2 million for 20 years
- $1 million for 30 years
During those first 10 years, when her children are young and her accumulated assets are relatively small, she has $5 million of coverage.
From years 11 through 20, she has $3 million. During the final decade, she has $1 million. Ideally, while that insurance ladder is stepping down, her net worth is stepping up.
That last sentence is really the whole strategy.
Why physicians can be particularly good candidates
Life insurance ladders can make particular sense for physicians because our financial lives tend to have an unusual trajectory.
We spend our 20s and often part of our 30s training while earning relatively little. Then our income suddenly increases dramatically.
Unfortunately, our net worth usually doesn't increase quite as quickly.
A new attending physician may earn $400,000 or $500,000 annually while simultaneously having student loans, a new mortgage, young children, relatively small retirement accounts, and a lifestyle increasingly dependent on attending-level income.
That's a lot of financial risk concentrated into one person's future earning potential. But a physician following a reasonable financial plan can dramatically change that picture over the next 10 to 20 years.
You pay down debt. You invest consistently. And you build retirement accounts. You potentially accumulate taxable investments and real estate. Eventually, you become financially independent.
That progression is why I recommend getting appropriate life and disability insurance early, when your future income represents such a huge percentage of your financial value.
Eventually, however, the goal is essentially to self-insure.
Who is the ideal candidate for a life insurance ladder?
I think the best archetype is a younger physician with significant financial obligations today who also expects those obligations to decrease substantially over time.
Think about someone in their early or mid-30s with young children, a mortgage, limited accumulated investments, and a high income that the household relies on.
At the same time, this physician has a high savings rate and a written financial plan that should result in significant wealth accumulation over the next few decades.
That person may need $5 million today. They probably won't need $5 million 25 years from now.
A ladder lets them design their coverage accordingly.
Life insurance ladders can also make sense when you have clearly defined temporary obligations. Maybe you want an additional $500,000 or $1 million of coverage until your children finish college. Or perhaps you want additional coverage during your highest-earning years while you are still building toward financial independence.
A shorter-term policy layered on top of existing long-term coverage can accomplish that.
What are the limitations?
The biggest limitation is obvious: you are predicting the future.
Your financial plan may say that you will need less insurance in 15 years. But life doesn't always follow the spreadsheet.
Maybe you have another child. Maybe your savings rate falls. Or maybe you buy a more expensive house. Maybe your spouse stops working. Maybe you take on additional financial responsibilities. You get it…there are a lot of maybes.
And once one rung of your ladder expires, replacing that coverage may be much more expensive. Even worse, a change in your health could make obtaining new coverage difficult or potentially impossible. That's why I would rather slightly over-insure for longer than build an overly aggressive ladder based on everything going perfectly.
There are also practical limits to how complicated you should make this.
You probably don't need five or six different policies expiring at carefully calculated intervals. In fact, multiple policies can carry separate policy fees that make excessive laddering inefficient. Two or three policies can accomplish most of what you are trying to do.
Complexity has a cost too.
Why I don't personally use a life insurance ladder
Despite all of this, I don't personally ladder my life insurance.
I bought a straightforward 30-year term policy near the end of training.
The amount of coverage was designed to give my wife and kids what they would need financially if something happened to me. And within our overall financial plan, I was comfortable maintaining that coverage rather than trying to gradually optimize it downward.
Could a ladder potentially have saved some money on premiums?
Probably.
But this is another example where I think physicians sometimes optimize past the point of usefulness. I wanted enough coverage for long enough that I didn't have to worry about it.
So that's what I bought.
The bottom line
A life insurance ladder is not a special insurance product.
It is simply a strategy using multiple term life insurance policies with different expiration dates so that your total coverage decreases as your financial need for insurance decreases.
For the right physician, it can be a very reasonable strategy.
A young physician with children, a mortgage, limited assets, and a high future income may need substantial life insurance today. If that same physician saves aggressively, pays down debt, builds investments, and eventually reaches financial independence, the need for insurance should decline over time.
A ladder can match that trajectory. But don't let optimization become complication. Keep it simple-ish.
The most important thing is not whether you have the perfect life insurance ladder. It is making sure that if people depend on your income, you have enough term life insurance to protect them.
Get that part right first. Then you can worry about the rungs.
What do you think? Do you have term life insurance? Do you have just 1 policy or did you construct a ladder? Why did you choose that strategy? Does it still make sense for your current situation? Let me know in the comments below!