When I finished medical training, I had a negative net worth of more than $500,000. At that point, the idea of worrying about inheritance taxes or estate planning seemed almost laughable. I was much more concerned about paying off student loans, saving money, and figuring out how to build wealth in the first place. But as my financial situation has changed, so has my perspective. And I've realized that understanding inheritance tax vs. estate tax is an important part of physician estate planning and protecting generational wealth.
For most of us, the initial goal is financial independence. We want to build enough wealth that we no longer have to worry about money, can practice medicine on our own terms, and have the freedom to spend our time however we choose.
But eventually another question comes into focus. What happens to everything we've built when we're no longer here?
It's not the most enjoyable subject to think about. However, particularly for physicians who accumulate substantial wealth over their careers, it's an important one.
And the rules have changed significantly over the past several years.
Inheritance Tax vs. Estate Tax: What's the Difference?
Let's start at a very basic level…
An estate tax is imposed on the estate of someone who has died, generally before the remaining assets are distributed to beneficiaries. The federal government imposes an estate tax, and several states have their own estate taxes.
An inheritance tax, on the other hand, is imposed based on what someone receives from a deceased person. These taxes exist only in certain states, and the amount owed often depends on the beneficiary's relationship to the deceased. For example, a surviving spouse may be completely exempt from inheritance tax, while a distant relative or unrelated beneficiary could owe a substantial amount.
And yes, in some situations, an estate tax and inheritance tax can both apply to the same transfer of wealth. Talk about getting it from both ends.
There Is No Federal Inheritance Tax
Thus, receiving an inheritance generally doesn't create federal income tax liability on the inherited property's value itself. However, you have to remember that income subsequently generated by inherited assets, withdrawals from certain retirement accounts, and gains on later sales may be taxable.
These distinctions become especially important as physicians accumulate investments, retirement accounts, businesses, and real estate.
Which States Have Inheritance Taxes in 2026?
Recently, Iowa eliminated its inheritance tax for deaths occurring on or after January 1, 2025. That leaves five states with inheritance taxes in 2026:
- Kentucky
- Maryland
- Nebraska
- New Jersey
- Pennsylvania
As you can see from the Tax Foundation's 2026 estate and inheritance tax analysis, rates and exemptions vary significantly depending on the state and the beneficiary's relationship to the deceased. Spouses are generally exempt, and close family members often receive more favorable treatment. More distant relatives and unrelated beneficiaries can face higher rates.
One important clarification is that inheritance taxes aren't determined simply by where the beneficiary lives. The deceased person's domicile, the location of certain assets, and the relevant state's laws can all matter.
So living outside one of these five states doesn't automatically mean an inheritance is free from every possible state inheritance tax.
Now let's move on to the estate tax…
The Federal Estate Tax Changed Dramatically in 2026
For years, there has been substantial uncertainty surrounding the federal estate tax exemption. Under the previous law, the historically elevated exemption was scheduled to decrease significantly after 2025.
However, the tax legislation enacted on July 4, 2025, changed that.
Beginning in 2026, the federal estate and gift tax exemption increased to $15 million per individual, with inflation adjustments scheduled for subsequent years.
For a married couple, that potentially means approximately $30 million in combined exemptions, assuming both spouses have their full exemptions available and the necessary planning and portability requirements are satisfied.
That's an enormous amount of money.
The federal estate tax can reach 40% on taxable amounts exceeding the available exemption. But because the exemption is so high, the vast majority of American families won't owe federal estate tax.
For physicians, this is reassuring. Even those who accumulate several million dollars over their careers may never approach the federal threshold.
But there's a catch.
Why State Estate Taxes May Matter More for Physicians
Although the federal estate tax exemption is now $15 million, state estate taxes can apply at significantly lower levels.
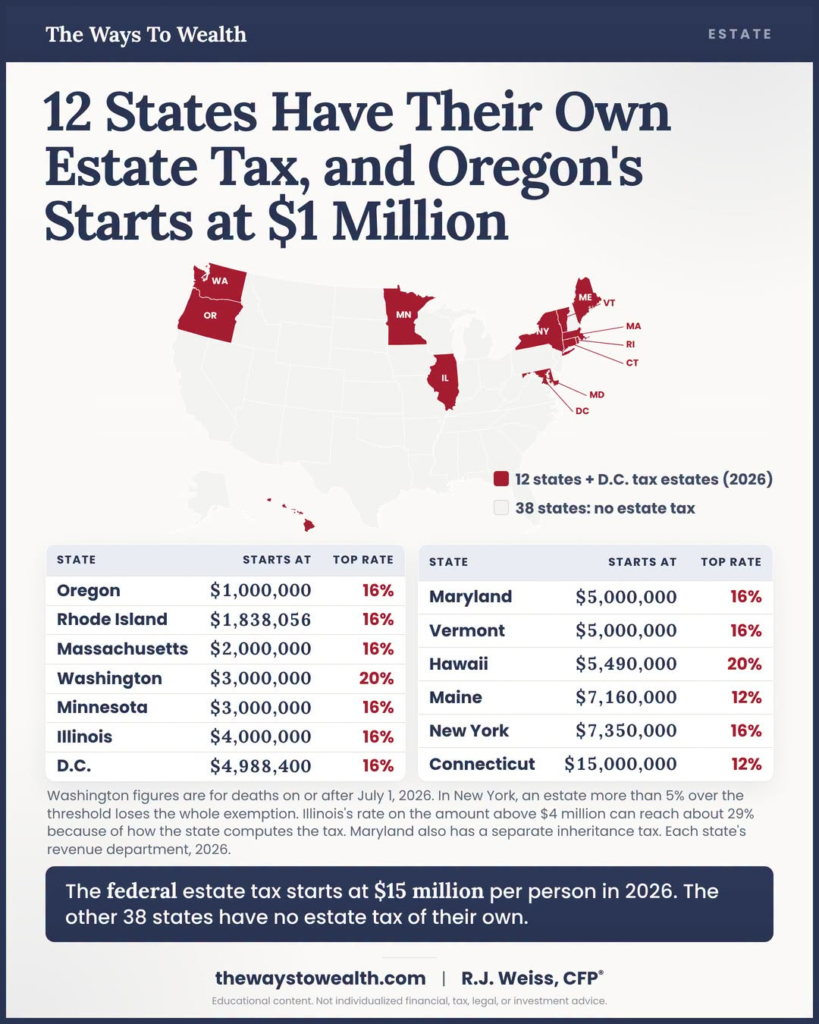
And this is particularly relevant to me because I live in New York. New York doesn't impose an inheritance tax, which I remember being pleasantly surprised about when I originally researched this topic.
However, New York does impose an estate tax. For deaths occurring in 2026, the New York estate tax exemption is $7.35 million. That's less than half the federal exemption.
And New York has an especially unusual provision known as the estate tax cliff.
Understanding New York's Estate Tax Cliff
In most tax situations, exceeding a threshold means you pay additional taxes on the amount above that threshold.
Unfortunately, New York's estate tax doesn't work quite that simply.
As the taxable estate rises above the exclusion amount, the benefit of the exclusion phases out rapidly. Once the estate exceeds 105% of the exclusion, the exclusion benefit disappears entirely.
For 2026, that cliff occurs at $7,717,500.
Consider a physician whose New York taxable estate is worth $7.5 million. That estate is only $150,000 above the state's basic exclusion. However, under the state's estate tax calculations, it could owe approximately $386,000 in New York estate taxes.
That's an enormous tax consequence relative to the amount by which the estate exceeded the exemption. For a physician approaching this level of wealth, thoughtful estate planning can become incredibly valuable.
- Locumstory is a free educational resource about locum tenens — not a staffing agency. No recruiters, no sales pitch.
- Straight answers on how locums works: schedule control, pay structure, W-2 vs. 1099, licensing and credentialing, and the tradeoffs nobody mentions.
- Free locums crash course, podcast, and newsletter — all built from real physician experience, not recruiter talking points.
- Worth a look whether you’re burned out, re-entering practice, testing a new market, or just want to know what your options actually are.
Why This Matters Even If You're Nowhere Near $15 Million
You might be reading this and thinking that you'll never have to worry about estate taxes because your net worth isn't anywhere close to $15 million.
And perhaps you're right. But remember that estate planning isn't just about your net worth today. It's about what your estate could be worth decades from now.
A physician who accumulates $3 million relatively early in their career could potentially see that wealth grow substantially over the following 20 or 30 years. Even without adding another dollar, $3 million growing at a hypothetical 7% annual rate would become approximately $12.2 million after 20 years.
Of course, those returns aren't guaranteed, and inflation would reduce the purchasing power of that future amount. But the example illustrates why estate planning deserves attention long before retirement.
This is particularly true for physicians who own businesses or rental properties. Those assets can appreciate significantly over time, potentially creating substantial estates even if the owners don't maintain enormous cash balances.
My wife and I have experienced how quickly net worth can change through active real estate investing.
And as that wealth grows, protecting it becomes increasingly important.
How Can Physicians Reduce Estate and Inheritance Taxes?
Fortunately, there are legitimate strategies that can help physicians manage estate taxes and preserve wealth for future generations. However, I want to emphasize that these strategies shouldn't be implemented simply because someone tells you they're sophisticated or tax-efficient.
Like every other financial decision, they should fit into a comprehensive plan. Don't let the tax tail wag the dog.
1. Use Annual Gift Tax Exclusions
One of the simplest estate planning strategies involves gifting assets during your lifetime.
For 2026, the annual federal gift tax exclusion remains $19,000 per recipient. That means an individual can generally give $19,000 to another person during the year without using any of their lifetime federal gift and estate tax exemption.
A married couple can potentially give $38,000 per recipient using both spouses' annual exclusions.
For example, a married physician couple with three children could potentially transfer $114,000 annually to those children without using their lifetime exemptions, assuming the gifts qualify.
Over time, that can make a meaningful difference.
And importantly, gifts exceeding the annual exclusion don't automatically trigger an immediate tax bill. They generally require reporting and reduce the available lifetime exemption, with actual gift tax typically arising only after the applicable exemption has been exhausted. The IRS explains these rules in its gift tax FAQ.
I've also previously discussed gifting and estate planning during a recession, including how changes in asset valuations can create planning opportunities.
2. Consider Trusts When Appropriate
Trusts can be incredibly useful estate planning tools, although their benefits depend heavily on how they're structured.
A revocable living trust, for example, can help with probate avoidance, privacy, and management of assets. However, it generally doesn't remove those assets from your taxable estate.
Certain irrevocable trusts, on the other hand, can potentially transfer future appreciation outside your estate when properly structured. Trusts can also establish how and when children receive inherited assets, which may be just as important as reducing taxes. But I would caution against assuming every physician needs an elaborate trust structure.
For many families, a straightforward estate plan with appropriate beneficiary designations, wills, and potentially a revocable trust is sufficient.
The goal should be protecting your family, not creating unnecessary financial complexity. I don't have any trusts set up to this point, although I suspect I will in the future. But the super complex ones don't really appeal to me.
3. Understand the Role of Life Insurance
Life insurance is another important consideration.
As I've discussed in my guide to life insurance for physicians, I strongly favor term life insurance for the overwhelming majority of doctors.
Its purpose is straightforward: protecting the people who depend on your income if you die prematurely.
Life insurance death benefits are generally received income-tax-free by beneficiaries, but that doesn't necessarily mean they're excluded from your taxable estate.
Ownership and beneficiary arrangements matter, and certain trusts can potentially help address estate inclusion.
This is one of the relatively limited circumstances where more sophisticated life insurance planning may be appropriate.
However, I still wouldn't recommend that most physicians purchase whole life insurance simply because someone presents it as an estate planning strategy. For the vast majority, term life insurance and a straightforward investment strategy remain more appropriate.
4. Die With Zero
Of course, there is another way to avoid these taxes…spend all of your money before you die.
Instead of leaving an estate for your kids when you die, take them on trips and buy them fancy things while you can actually see them enjoying it.
I've shared my thoughts on the Die With Zero principle before. And while I don't agree with all of the premises, I do kind of agree with this one. I definitely want to leave some money for my kids. But I also want to use a whole lot of it enjoying life with them before I am gone!
So there is a balance…
- Locumstory is a free educational resource about locum tenens — not a staffing agency. No recruiters, no sales pitch.
- Straight answers on how locums works: schedule control, pay structure, W-2 vs. 1099, licensing and credentialing, and the tradeoffs nobody mentions.
- Free locums crash course, podcast, and newsletter — all built from real physician experience, not recruiter talking points.
- Worth a look whether you’re burned out, re-entering practice, testing a new market, or just want to know what your options actually are.
Don't Forget About Retirement Accounts and Inherited Assets
Another important aspect of physician estate planning involves the types of assets you're leaving behind.
Not all inheritances receive identical tax treatment.
For example, inherited taxable investments and real estate generally receive a basis adjustment to fair market value at death under current federal law, subject to exceptions. That can substantially reduce capital gains taxes on appreciation that occurred during the original owner's lifetime.
However, inherited traditional IRAs and other pretax retirement accounts generally don't receive the same treatment.
Many non-spouse beneficiaries must distribute inherited retirement accounts within ten years under the SECURE Act rules, and additional annual distribution requirements can apply depending on the circumstances.
These distributions can create significant income tax obligations for beneficiaries. This is one reason estate planning shouldn't focus exclusively on avoiding estate taxes. The income tax consequences of inherited assets can be equally important.
For physicians with substantial retirement savings, understanding these rules and reviewing beneficiary designations should be part of the overall financial plan.
Estate Planning Is About More Than Taxes
I think it's easy to get so caught up in the financial aspects of estate planning that we forget its actual purpose. For me, the most important consideration isn't necessarily minimizing every possible dollar of taxes. It's making sure my wife and children are protected and that the wealth we've worked so hard to build ultimately serves them well.
That means having appropriate insurance, maintaining accurate beneficiary designations, and making sure the right legal documents are in place.
It also means thinking about how wealth should be passed down.
Do I want my children to receive everything immediately? Would a trust provide better protection? How can I help them develop the financial knowledge and habits necessary to manage an inheritance responsibly?
Those are important questions regardless of whether an estate will ever owe a dollar in taxes.
I've written before about how we approach saving for our children's education. To me, estate planning is another extension of that same philosophy: using the financial resources we build today to create opportunities for our family tomorrow.
And just as importantly, helping the next generation develop the knowledge and responsibility to use those resources wisely.
Incorporating Estate Planning Into Your Written Financial Plan
As readers know, I'm a huge believer in having a written financial plan. It's been the foundation of our financial transformation, and I believe every physician should have one. But financial plans aren't static.
As your income, assets, family situation, and goals evolve, your plan needs to evolve as well.
I've shared examples of this in the changes we've made to our own financial plan.
Estate planning should be part of that process.
At a minimum, physicians should periodically review their wills, powers of attorney, healthcare directives, life insurance coverage, and beneficiary designations.
For families with children, establishing appropriate guardianship provisions is particularly important.
And as net worth increases, especially for physicians approaching state estate tax thresholds, consulting an experienced estate planning attorney becomes increasingly valuable. I would also recommend revisiting your estate plan after major life events, including marriage, divorce, the birth of a child, a substantial inheritance, or a significant change in financial circumstances.
After all, a financial plan is only useful if it reflects your actual life.
The Bottom Line on Inheritance Tax vs. Estate Tax
When I originally learned about inheritance taxes, I viewed them primarily as another interesting financial concept that physicians should understand.
Now, several years later, I see the subject a little differently.
As my own family has grown and our financial situation has improved, the importance of protecting and eventually transferring wealth has become much more apparent.
The good news is that the federal estate tax exemption has increased significantly, and most physicians won't need to worry about federal estate taxes. However, state estate and inheritance taxes remain important considerations, especially in states like New York where the exemption is substantially lower.
And even for physicians who will never owe estate taxes, having a thoughtful estate plan is essential.
Ultimately, financial freedom isn't just about accumulating enough money to live the life you want. It's also about ensuring that the wealth you've built continues to support the people and priorities that matter most to you.
That's what generational wealth really means to me.
What do you think? Have you incorporated estate planning into your financial plan? Do you worry about inheritance or estate taxes, or are you more focused on ensuring your family is protected? And how do you approach the question of passing wealth to your children? Let me know in the comments below!