I recently learned something new about my 403(b).
Normally, that would not be particularly noteworthy. Except that I have had this 403(b) for about six years. I have written extensively about the account, including an entire deep dive into exactly how I invest my 403(b). I review it every year when I rebalance my portfolio. And I have literally published the individual investments within the account for anyone on the internet to see.
Yet somehow, I had completely missed something pretty fundamental about how the account itself was structured.
The funny part is that I discovered it almost completely by accident. And the whole experience turned into a pretty great example of one of the biggest problems with personal finance: it is often way more complicated than it needs to be.
But it also reinforced an equally important lesson. You don't actually need to understand every tiny detail of personal finance. You need to understand which details actually matter.
Why was my 403(b) showing up twice?
This whole thing started when I entered my TIAA 403(b) into a wealth tracking software.
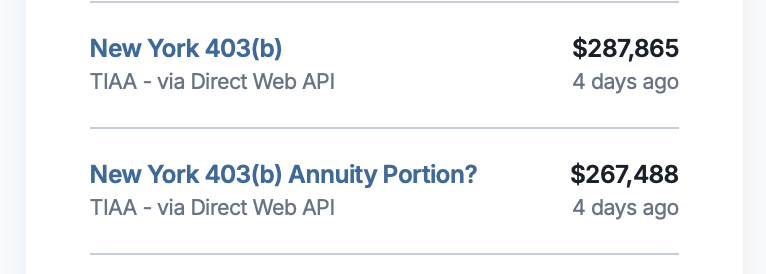
I was getting all of our accounts loaded into the software when I noticed something strange. My TIAA 403(b) showed up as two separate accounts, each with about half of the total value. That didn't make any sense to me.
As far as I knew, I had one 403(b). I contributed to one 403(b). When I logged into TIAA, I thought about everything there collectively as my retirement account. I certainly wasn't making two separate contributions or consciously managing two separate accounts.
Initially, I assumed it was some sort of glitch with the software. Maybe TIAA was just transmitting the information strangely. Maybe I had linked the account incorrectly. Either way, I didn't think too much of it.
Eventually, though, curiosity got the better of me and I asked a financial advisor friend why this was happening. That's when I learned something that I probably should have known a long time ago.
My TIAA retirement plan contains investments that are structured in two fundamentally different ways. Some are more traditional mutual/index fund-style investments, while others are technically held through annuity contracts.
Wait…what?
Apparently, I own an annuity
This was particularly funny to me because when I originally selected TIAA as the provider for my 403(b), I specifically wrote about another option available to me that was a “Fidelity Annuity.”
And I ruled it out because, in my own words: “I knew I didn't want an annuity.” Welp, joke's on me!
Because while I certainly didn't buy the type of high-fee variable annuity that I generally warn physicians to be very cautious about, I eventually learned that some TIAA retirement investments are technically structured as annuities. This is where terminology in personal finance starts making things unnecessarily confusing.
My 403(b) is still my 403(b). That is the tax-advantaged retirement account provided through my employer. But inside that retirement account, TIAA can offer different types of investment vehicles. Depending on the plan, those can include mutual funds, annuity-based investments and even a brokerage component that provides access to additional investments.
This unusual structure makes more sense when you understand TIAA's history. The organization has long served employees of universities, educational institutions and nonprofits, and annuities have been a central part of its retirement system for decades. In fact, the “A” in TIAA originally stood for “Annuity.”
According to TIAA's own explanation of its investment options, its retirement plans can include mutual funds as well as fixed and variable annuities.
So the wealth tracking software wasn't necessarily making a mistake when it separated my TIAA assets. It was recognizing two legally different pieces of what I had always mentally lumped together as one retirement account.
So what exactly am I invested in?
This is where things get even more interesting.
As I shared in my 2025 investment portfolio review, my TIAA 403(b) is currently invested across a collection of Vanguard, TIAA and CREF investments covering U.S. stocks, international stocks, bonds and real estate.
At the end of 2025, the overall account was approximately 81% stocks, 16% bonds and 4% real estate. And here's where we need to separate what actually matters from what doesn't.
I didn't accidentally discover that half of my retirement portfolio had been sitting in some crazy insurance product that I didn't understand for six years. The investments were still doing exactly what I thought they were doing.
My U.S. stock allocation was still invested in U.S. stocks. My international allocation was still international stocks. And my bond allocation was still bonds. The legal wrapper around certain investments didn't suddenly change the underlying economic exposure that I had intentionally chosen.
That distinction is really important.
• Most side gigs take time to build. This one pays fast.
• I do short, physician-only surveys on Sermo between cases and get paid for my input.
• They take just a few minutes and the money hits PayPal or gift cards right away.
• It’s not replacing my OR income, but it covers the little things that have a big impact—gifts, kids' activities, or the next date night.
An annuity inside a 403(b) isn't necessarily what you think it is
When most physicians hear the word “annuity,” they probably picture an insurance salesperson trying to convince them to put a huge chunk of their retirement savings into a complicated product with high fees, surrender charges and promises of guaranteed income.
But that's not necessarily what we're talking about here.
TIAA's retirement system includes variable annuity accounts, including certain CREF investments. These are insurance contracts, but their value can fluctuate based on the performance of the underlying investments. From the investor's perspective, some of these investments can therefore behave a lot more like the stock or bond investments you are accustomed to owning than the stereotypical annuity you may have in your head.
Meanwhile, something like TIAA Traditional is a fixed annuity and operates very differently. Rather than fluctuating directly with the stock market, it provides contractual guarantees around principal and interest, subject to TIAA's claims-paying ability.
That distinction can actually matter.
Depending on the specific TIAA contract, money invested in TIAA Traditional may have restrictions on how quickly it can be transferred out. Some contracts can require money to come out over a period of years rather than allowing an investor to immediately move the entire balance somewhere else.
Now you've got my attention.
Liquidity restrictions can affect my financial plan. Higher fees can affect my financial plan. An investment behaving differently than I thought it did can certainly affect my financial plan.
The fact that one of my existing market-based investments happens to be legally structured as a variable annuity, on the other hand, may not change my written financial plan at all.
And that's really the key lesson from this entire experience.
What actually matters to me as the investor?
Once I understood what was going on, I started trying to strip away all of the terminology and ask the questions that actually matter.
What am I invested in? What is my overall asset allocation? How much am I paying in fees? Are there restrictions on moving my money? Does anything about this structure change my risk, expected return, liquidity or ability to use the money according to my financial plan?
Those questions matter a lot.
Whether my wealth tracking software categorizes the investments as one account or two accounts mostly doesn't.
Even the fact that an investment is technically structured as a variable annuity may matter much less than the word “annuity” initially makes it seem. The label sounds dramatic because I have strong opinions about many annuity products. But labels aren't nearly as important as understanding what you actually own.
There is another wrinkle here that I think is worth emphasizing. Holding an annuity investment inside a 403(b) doesn't somehow give you an extra layer of tax deferral. The 403(b) is already a tax-advantaged retirement account. Likewise, owning an annuity-based investment doesn't necessarily mean that you have “annuitized” your retirement savings and committed yourself to receiving a predetermined monthly payment for the rest of your life.
Those are different concepts that happen to share the same word.
Welcome to personal finance!
This is exactly why personal finance feels so hard
I spend a ridiculous amount of time thinking, reading and writing about personal finance. I have been managing our family's finances for years, created a written financial plan, built an investment portfolio and written hundreds of articles about this stuff.
And I still didn't know this about my own retirement account.
So imagine someone who finishes medical training at age 35, starts their first attending job and gets handed a giant benefits packet. Suddenly, they are expected to understand 403(b)s, 401(k)s, 457(b)s, Roth IRAs, traditional IRAs, mutual funds, ETFs, expense ratios, asset allocation, annuities, insurance contracts, vesting schedules, tax treatment and whatever alphabet soup their employer happens to throw at them.
It's absurd when you really think about it.
Most of us receive essentially zero formal financial education during medical school or residency. Yet almost immediately after training, we are making decisions involving hundreds of thousands and eventually millions of dollars.
The natural reaction is to think that we need to understand every single detail before we can make a good financial decision. And when we inevitably realize that we don't understand everything, it's easy to throw our hands up and decide personal finance is simply too complicated.
But I don't think that's the right response either.
You don't need a PhD in your 403(b)
One of the biggest realizations in my own financial journey has been that understanding personal finance does not mean understanding every obscure rule, investment structure or tax nuance.
In fact, trying to understand every detail can become counterproductive. It's like how I don't need to still remember and understand the Kreb's cycle (I just threw up in my mouth) to perform a microsurgical breast reconstruction.
You can spend hours comparing two index funds that differ by a few basis points while ignoring your savings rate. You can agonize over whether your portfolio should contain 15% or 17% international stocks while panic-selling during the next bear market. And you can optimize every tiny corner of your retirement accounts while never actually creating an overarching investment strategy.
That's why I am such a big advocate for creating a written financial plan.
My plan tells me how much we save. It tells me what my asset allocation should be. It tells me what types of investments I use and when I rebalance. Most importantly, it prevents me from reacting emotionally every time the market changes or I learn something new.
The mechanics underneath those decisions can sometimes be complicated.
The strategy doesn't need to be.
• Most side gigs take time to build. This one pays fast.
• I do short, physician-only surveys on Sermo between cases and get paid for my input.
• They take just a few minutes and the money hits PayPal or gift cards right away.
• It’s not replacing my OR income, but it covers the little things that have a big impact—gifts, kids' activities, or the next date night.
Learn enough to know what moves the needle
There is obviously a balance here.
We shouldn't use “personal finance is complicated” as an excuse to remain financially ignorant. Physicians do this all the time. We tell ourselves that we are too busy or that finance is too confusing, so we outsource everything without understanding any of it.
That's dangerous because nobody will ever care about your money as much as you do.
But the opposite extreme can be dangerous too. There is an almost unlimited amount of financial minutiae available to obsess over, and at some point the pursuit of optimization starts creating complexity without meaningfully improving the result.
What actually moves the needle is usually pretty boring.
Your savings rate matters. Your asset allocation and willingness to stick with it matter. Fees matter. Diversification matters. Taxes matter. Your behavior during periods of market volatility matters enormously.
Whether your retirement platform displays one piece of your 403(b) separately because of the legal structure of an investment probably doesn't.
Unless, of course, that structure introduces higher fees, guarantees, liquidity restrictions or other features that affect your plan.
That's the filter I ultimately came away with from this experience: Does this new piece of information actually change my financial strategy, costs, liquidity or the risk that I am taking?
If the answer is yes, I need to understand it. If the answer is no, I need to understand it well enough to recognize that fact and then move on.
My 403(b) didn't change. My understanding of it did.
Ultimately, nothing changed about my investments when I discovered all of this.
The same money was invested in the same underlying assets before and after I asked my financial advisor friend why two TIAA accounts were appearing on my screen. My overall investment strategy didn't change. Neither did my risk tolerance or long-term goals.
I simply understood the plumbing a little better.
And I'm glad I do.
There have absolutely been times when I have changed my financial plan because new information or changes in our circumstances justified it. But learning something new doesn't automatically mean that you need to do something new.
Sometimes the appropriate response is simply to learn how something works, figure out whether it matters, and then keep following the plan.
That's ultimately what I did here.
Because personal finance is complicated enough already. The trick isn't learning every detail.
It's learning which details actually matter.
What do you think? What investment details are important on your mind? Which ones are better ignored? Would it have mattered if I never realized this about my investment account? Let me know in the comments below!